
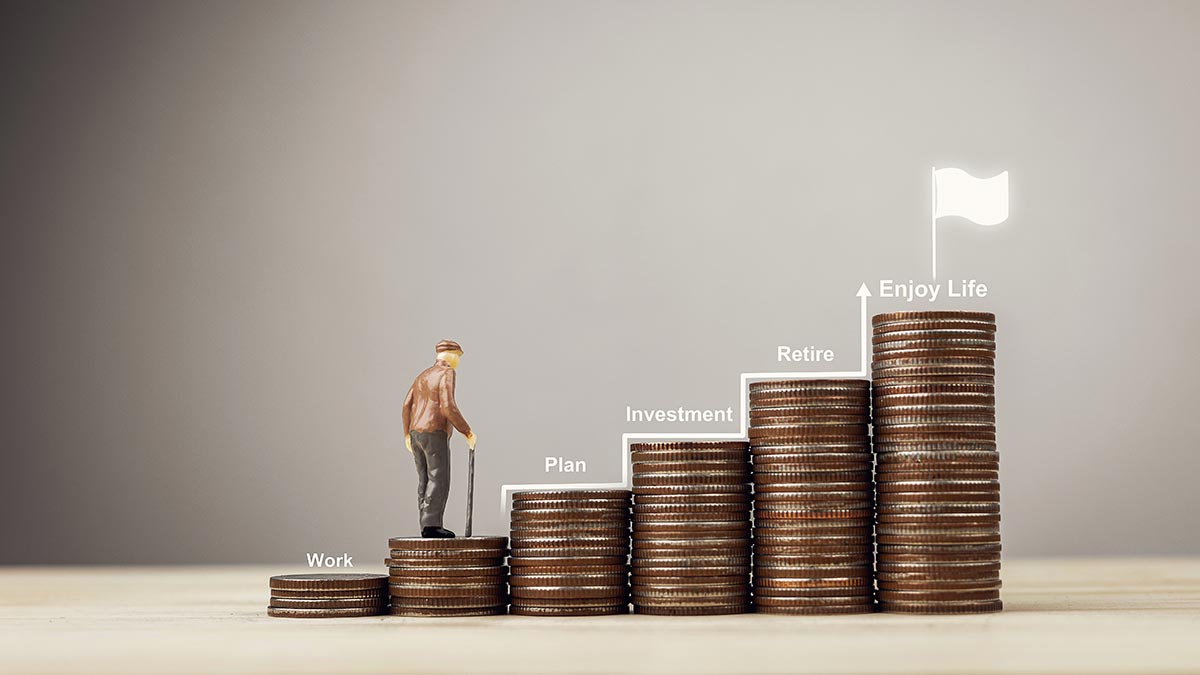
When should you start planning retirement? Of course, the earlier, the better. But what if you missed a few buses? Is 50 too late? Not necessarily. Retirement planning can begin at any age, and 50 still offers a valuable opportunity to build a focused financial plan. While starting early provides the advantage of a longer compounding period, a well-structured approach at 50 can still help build meaningful retirement readiness.
The first step is to evaluate current expenses, savings, liabilities, health care needs and the income required to maintain one’s lifestyle after retirement. With life expectancy increasing and retirement potentially spanning 30 years or more, the focus should be on both building a retirement corpus and creating a sustainable income stream.
Key questions include whether current savings will be sufficient to support the desired lifestyle? How rising health care costs will be managed? Should there be a plan to generate regular income when active earnings stop?
“For many individuals, retirement planning at 50 is less about starting from scratch and more about evaluating the retirement gap between existing savings and future financial needs, and taking focused steps to bridge it,” said Manish Alagh, head (partnerships and direct distribution), Kotak Mahindra Life Insurance. “Life insurance can also play an important role in retirement planning. Solutions such as annuity products can help convert accumulated savings into a regular stream of income, providing greater financial certainty and helping individuals maintain their financial independence throughout retirement.”
When retirement planning begins later in life, the focus should be on maximising savings efficiency and making the most of the remaining earning years rather than chasing high returns. Existing assets such as provident fund balances, gratuity benefits, deposits, investments and life insurance savings should be consolidated to assess the corpus already built and identify the retirement gap.
“One can increase retirement contributions with every salary increment or bonus. At the same time, one can adopt an asset allocation strategy that balances growth and capital preservation. Factor in inflation and rising health care costs while estimating future income needs. Consider extending one’s working years, where feasible, to strengthen retirement readiness and focus not only on wealth accumulation but also on creating sustainable retirement income,” said Alagh.
Risk management is particularly important for those starting late. Taking disproportionate market risk to generate higher returns can jeopardise the corpus at precisely the stage when there is less time to recover from a setback. An emergency fund can prevent unexpected expenses from disrupting retirement savings, while high-cost debt should ideally be reduced before retirement. Inflation, particularly health care inflation, also needs to be factored into future income requirements.
“Quite often, the problem isn’t that the investor has too little money; it is that the money is sitting in the wrong places—too much concentration, too much idle cash, unsuitable investment products or investments taken for reasons other than the retirement objective,” said Harsimran Sandhu, professor and area chairperson, finance, Institute of Management Technology, Ghaziabad. “The other thing I would caution against is trying to recover lost time through derivative trading or concentrated bets in equity markets. Equity markets will give you opportunities, but there will also be periods when things go wrong.”
For late starters, one of the most effective strategies is to increase the savings rate and make existing money work harder. This could involve regulating discretionary spending, optimising investments and using tax-efficient retirement instruments. A balanced portfolio with exposure to growth assets can help generate long-term returns, while regular reviews can ensure that investments remain aligned with retirement goals.
Extending one’s working years by even a few years can also make a significant difference. It allows additional time for savings to accumulate while reducing the number of years that the retirement corpus needs to fund.
“Investors should first evaluate the required retirement corpus and then determine the monthly investment required to reach that goal. As retirement approaches, the portfolio should gradually become more conservative with 60:40 across equity and debt. Another important factor is to step up investments as income rises and deploy existing idle capital efficiently. Even an additional five years of disciplined investing can help to build a substantial corpus because of the compounding effect,” said Krishanu Choudhary, director and unit head, Anand Rathi Wealth.
Choudhary recommends maintaining emergency funds, health insurance and life insurance separately from the retirement portfolio and reducing high-cost debt before retirement.
The biggest challenge for someone beginning retirement planning in her 50s is the shorter compounding period. “Someone starting at 30 has considerably more time to build wealth than someone starting at 50, even if both invest the same amount. For instance if someone started investing 10,000 at 30, retiring in 60 can create a corpus of Rs3.75 crore. However, someone starting at 50 with even Rs40,000 can create a corpus only Rs1 crore. This indicates a key challenge of starting late as investor has less time to for compounding and therefore needs to compensate through a significantly higher investment and there is also much less room for investment mistakes or excessive risk-taking as the retirement approaches,” said Ramakant Yadav, founder, Scalar Field.
Starting at 50 means having to save more, work longer and accept less room for error. But it is never too late. The key is to replace the lost years of compounding with disciplined savings, sensible asset allocation, adequate protection and a realistic retirement income plan.